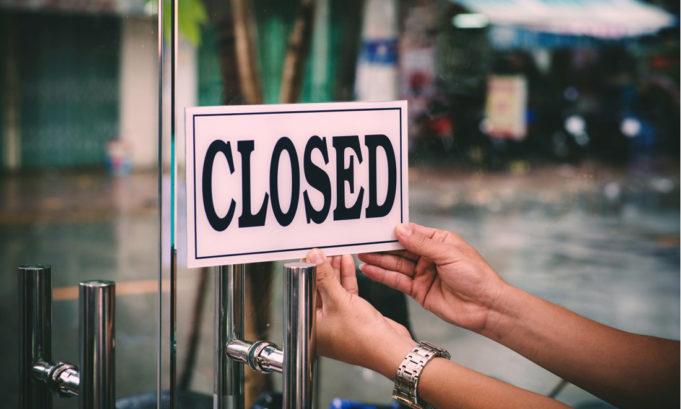
Closing a business may seem straightforward, but the legal entity of an LLC continues to exist even after operations cease. A business owner can shut down their storefront and inform customers that the business is finished, yet the LLC remains intact. This ongoing legal entity may still have obligations such as filings, taxes, contracts, and debts that require resolution.
The legal existence of a company is initiated through formal steps, with the registration of the LLC establishing its status under state law. To terminate this legal existence, formal actions are equally necessary. The process for winding down an LLC varies based on the state where it was established and where it conducts business, making closure a multi-step procedure rather than a single act.
A Clean Exit Involves Multiple Steps
To achieve a proper exit, owners must navigate several layers. This includes obtaining approval for dissolution, winding up the company, addressing tax and creditor issues, and completing any necessary termination filings. The specific sequence of these steps can differ by state.
Understanding the Distinction Between Operations and Legal Termination
Shutting down operations is an operational choice, while dissolution and termination are legal processes. This distinction can be overlooked, especially in small businesses with minimal assets and no employees.
The U.S. Small Business Administration emphasizes the risks associated with failing to properly dissolve an LLC or corporation in every state where it is registered. Neglecting this legal process can result in ongoing tax liabilities and filing obligations. Business owners are also advised to cancel permits and registrations, manage employee matters, settle financial commitments, and maintain necessary records.
What Winding Up Actually Entails
The winding-up phase is characterized by the company resolving its remaining affairs rather than continuing regular business operations. The specifics of this process are shaped by state law and the LLC’s operating agreement, but the goal remains the same: to identify outstanding issues, address them systematically, and document the outcomes.
This process may involve several tasks, including collecting owed funds, settling debts and liabilities, managing inventory and equipment, terminating leases and licenses, and distributing remaining assets only after fulfilling higher-priority obligations. Owners should avoid simply dividing up the remaining funds; creditor rights, tax responsibilities, state regulations, and the operating agreement will dictate the order of payments. In cases where the company cannot satisfy its obligations, seeking legal and accounting advice becomes crucial.
Tax Responsibilities May Extend Beyond Closure
The final payment from a customer often does not mark the end of a business’s administrative duties. A closing LLC may still be required to fulfill federal, state, and local tax obligations. The federal requirements will depend on the LLC’s tax classification, while state responsibilities vary based on the jurisdictions involved.
For businesses with employees, final payroll obligations must be addressed. Additionally, items such as sales tax accounts, industry permits, assumed business names, and local registrations may require attention. In certain states, additional tax steps may influence the termination process, necessitating that owners check with the appropriate business filing agency and tax authorities in each relevant state.
Managing Digital Assets During Closure
In today’s digital age, an LLC can leave behind more than just physical assets. Domain names, websites, email accounts, cloud storage files, social media profiles, software subscriptions, and customer data may all require careful consideration before access is discontinued.
Before shutting down digital services, owners should determine what needs to be preserved, transferred, sold, archived, or securely deleted. Important domains and business records should not be lost in the process.
A practical digital shutdown may involve exporting necessary records, transferring valuable domains or intellectual property, updating customer-facing information, canceling paid services only after retrieving essential data, and revoking access for former employees and contractors. These actions should complement the legal and financial closure rather than occur in isolation.
Planning for a Successful Exit
Just as the formation of a business requires careful planning, so too does its closure. Business owners must understand who is authorized to approve dissolution, what liabilities exist, which assets remain, what filings are necessary, and which records must be retained.
For companies with multiple members, employees, valuable assets, or operations across several states, consulting with an attorney or accountant may be essential. Even for simpler businesses, confirming compliance with both state and federal regulations is important.
A business can cease trading before its legal and administrative responsibilities are fully resolved. Recognizing winding up as a distinct phase helps owners fulfill their obligations, preserve necessary records, and differentiate between a dormant business and one that has been officially terminated. A well-planned exit allows owners to conclude their business on clear and organized terms.